Oct 15, 2026
AI Meets Agents: How Homa’s Arman Javaherian Is Bringing Faster Help and Bigger Savings to the Homebuying Market
Homa pairs AI with licensed agents and on-demand showing specialists, so homebuyers get faster, more responsive help and keep thousands more at closing.
Traded Editorial
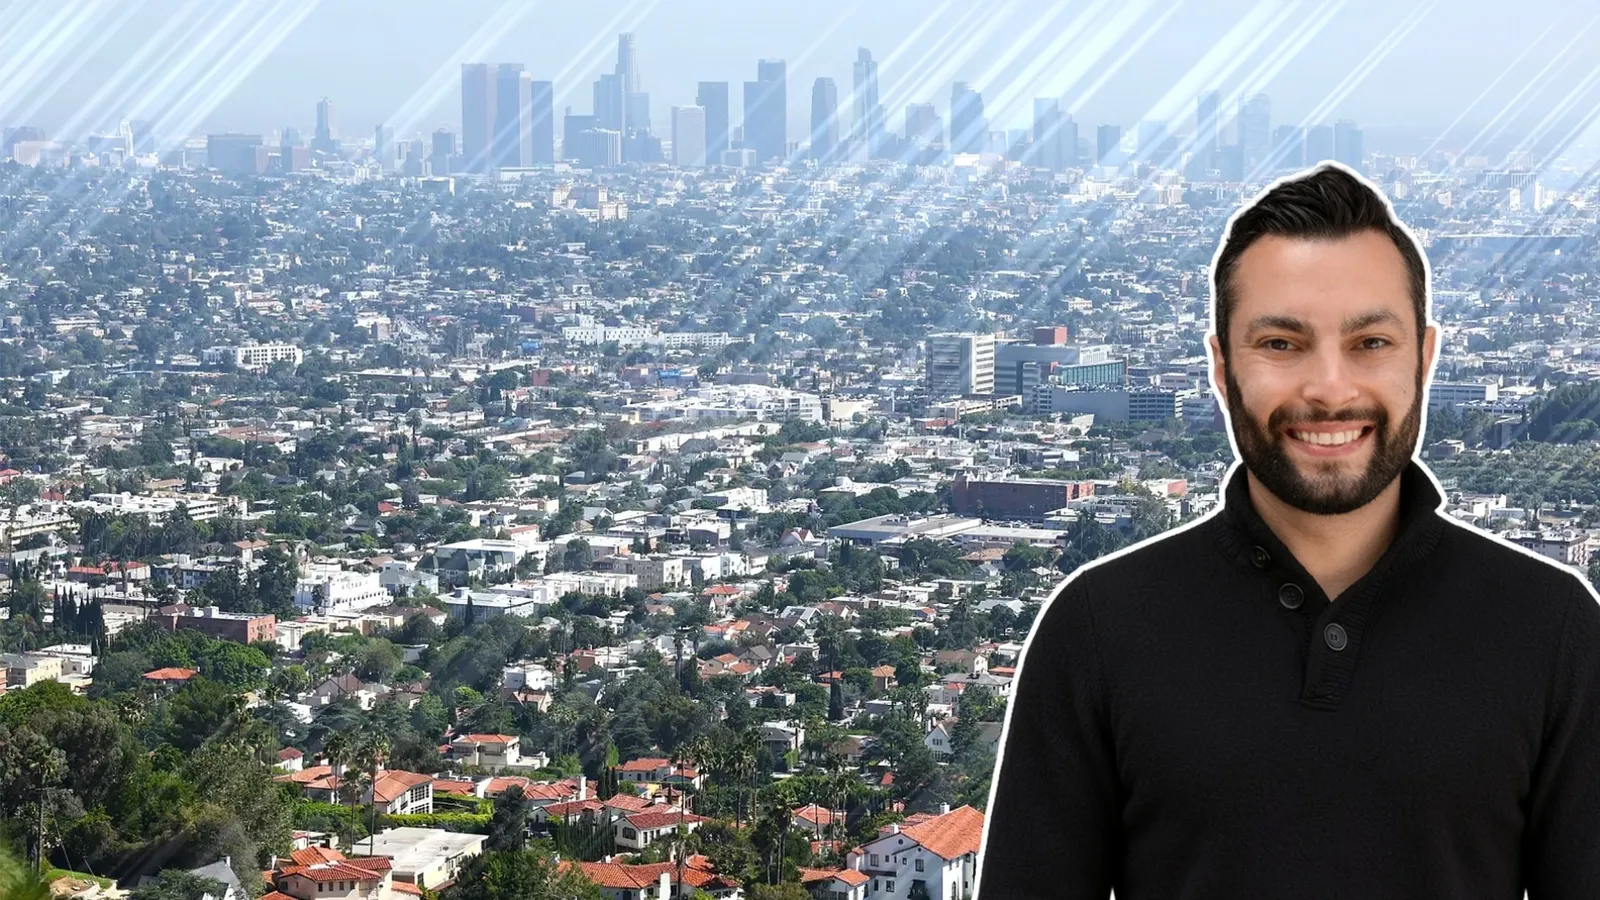
Homa co-founder Arman Javaherian on leaving Zillow, the NAR settlement that created an opening for a new brokerage model, giving buyers up to 2% back, and why AI could make real estate agents 50 times more efficient
For Arman Javaherian, the problems with residential real estate became obvious long before he started Homa.
After spending roughly six years at Zillow building its Premier Agent platform, Javaherian saw millions of homebuyers search for properties online before being handed off to traditional agents. Buyers were already doing much of the work themselves, from finding homes to researching neighborhoods, yet they could still face tens of thousands of dollars in buyer-agent commissions.
That disconnect eventually became the foundation for Homa, a technology-driven homebuying platform that combines AI, licensed real estate professionals, and on-demand showing specialists. Today, Homa operates in Florida, Texas and California and markets a model that charges buyers 1% while returning the remaining seller-paid buyer-agent commission, up to 2%, to the buyer.
Homa announced today that it raised $5 million in seed funding led by Quiet Capital, with participation from Restive Ventures and Cambrian Ventures. The round enables expansion for the industry-first platform that guides buyers through search, touring, negotiation, and closing. Homa is now available across California and, as of today, lets buyers secure a mortgage inside the platform.
The NAR Settlement Created the Opening
Javaherian's path to Homa runs through Zillow, Crunchbase, and ultimately the 2024 NAR settlement
At Zillow, he was responsible for the Premier Agent platform, connecting homebuyers with real estate agents. The experience gave him a close look at where the traditional model broke down
"I saw firsthand the struggles in the industry"
The August 2024 NAR settlement changed the environment by requiring MLS-participating agents to enter into written buyer agreements before touring homes. It also changed how buyer-agent compensation is handled, creating more transparency around who pays the agent and how much they receive
For Javaherian, that was the moment the opportunity became clear
"The NAR settlement was the moment"
He had already started working on Homa's prototype with his co-founder by June 2024. The company raised its pre-seed in December and began working on the product in January 2025.
Giving Most of the Commission Back
Homa's central pitch is straightforward
The platform keeps 1% of the purchase price and returns the remaining commission to the buyer when the seller is offering more than that
On a $1 million transaction with a 3% buyer-agent commission, Homa would receive $30,000, keep $10,000 and return $20,000 to the buyer as a credit
That credit can be used toward closing costs, the purchase price or a mortgage rate buydown. Homa currently advertises credits of up to 2% and says that a rate buydown can reduce the mortgage rate by as much as 0.75%, depending on the transaction and lender.
For buyers facing high home prices and mortgage costs, Javaherian believes the economics can make a meaningful difference
"By doing it our way, we only take 1% as a fee, and we give everything else back to the home buyer"
The Uber Model for Showings
The other major difference is how Homa handles the home tour.
Instead of assigning one buyer's agent to handle every showing, Homa allows buyers to request a tour through the platform. The request is sent to local showing specialists, with the first available person accepting the assignment
Javaherian compares the experience to Uber
The showing specialists aren't there to sell the property. They can discuss the neighborhood and schools, but they don't provide advice about the property itself. Once a buyer is ready to make an offer, the transaction moves to one of Homa's licensed agents
That separation is central to Homa's economics
Turning One Agent Into 250 Transactions
Traditional agents are limited by how many buyers they can personally serve. Javaherian estimates the average agent handles roughly 5.5 transactions a year, while Homa's senior licensed agents can potentially handle as many as 250 transactions annually.
"We're 50xing their kind of efficiency and capability"
The model divides the work among showing specialists, AI, senior licensed agents, and closing coordinators.
Homa currently has one senior broker per state, according to Javaherian, with each able to handle up to 20 transactions a month before another broker needs to be added.
The company believes that structure can scale far more efficiently than simply adding another traditional agent for every increase in transaction volume.
AI Becomes the Buyer's Research Team
Homa isn't trying to eliminate humans from the transaction.
It is trying to use AI to determine where humans are actually needed.
The platform analyzes properties, pricing, disclosures, and transaction data before connecting buyers with licensed professionals for negotiations and other critical steps.
Its bargaining-power score is one of the platform's key features. Javaherian says the system can tell buyers when a property is overpriced or when they should walk away.
"We tell buyers to walk away all the time"
That is also part of Homa's strategy for building trust. The company doesn't make money simply because a buyer spends more on a house, so Javaherian argues that its model allows the platform to tell customers when a deal doesn't make sense
Homa says its AI has already handled more than 120,000 interactions with homebuyers in recent months.
From Florida to a National Platform
Homa launched in Florida because Javaherian initially viewed it as a strong buyer's market for an AI-driven model. The company later pivoted after discovering that unrepresented buyers could face resistance from listing agents
Texas became the next market, followed by California
Homa's website now lists all three states as active markets, with more than 14,000 registered homebuyers and an average stated credit of $15,000 based on a $750,000 purchase.
The company has its sights on additional high-population states, including Illinois, New York, Georgia, Washington and North Carolina
Mortgage Is the Next Piece
Homa is also expanding beyond brokerage
Javaherian says mortgage is a major part of the company's strategy because financing is often one of the biggest sources of closing delays and risk
The company has established a mortgage operation and wants to eventually integrate the entire transaction into one platform, including real estate, mortgage, title, insurance, and eventually seller services.
"We want Homa to be that umbrella brand"
The vision is less a cheaper brokerage than a single operating system for the home purchase.
Building the Real Estate Agent in Your Pocket
The next major product is Homa's mobile app
Javaherian, whose background includes mobile development at Zillow, says the team is building an experience where buyers can communicate with AI, bring in human agents when necessary, and receive property recommendations based on what they actually do during the home search
That last piece is particularly important
Traditional listing platforms know what properties buyers click on. Homa wants to know what properties they actually tour, what they like, and what they reject.
"We can ask you for feedback about each of those homes and then use that to make the recommendation"
The company's broader thesis is that AI can make homebuying more efficient without removing the licensed professionals required to complete the transaction.
For Javaherian, that regulatory complexity may actually be an advantage
"It's a very human-centric" industry
That could make residential real estate one of the more interesting places for AI to compete, not by eliminating the agent overnight, but by fundamentally changing what the agent does and how much the consumer has to pay for it.