Ran Eliasaf’s Northwind Group Doubles Debt Fund Target to $1 Billion
Northwind Group’s founder is scaling a private-credit platform built on first-lien lending, disciplined underwriting, and financing projects banks increasingly leave behind.
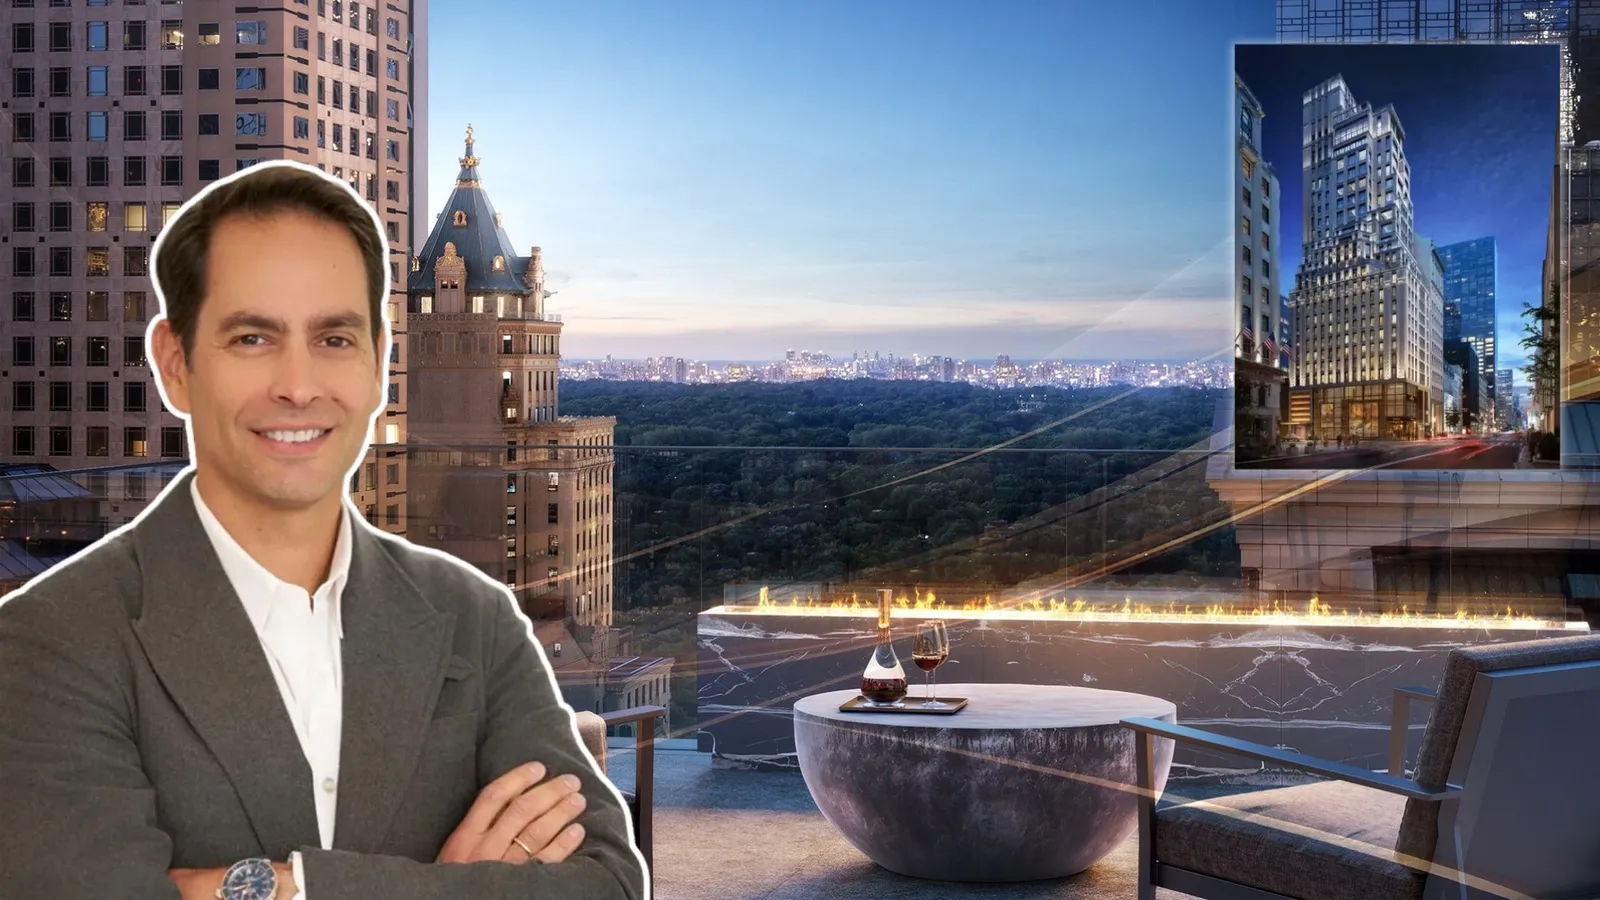
Ran Eliasaf has built Northwind Group around a straightforward bet: when banks pull back, disciplined private lenders can step in and finance real estate projects that still have a viable path forward.
That strategy is gaining scale. Northwind recently closed its third real estate debt fund with $1 billion in committed capital, doubling its original $500 million target. The fund has already originated $1.5 billion in loans, highlighting the firm’s growing role in financing residential properties and office-to-residential conversions.
Eliasaf’s approach centers on first-lien loans, experienced sponsors, and protecting downside rather than betting on a quick market recovery.
From Equity Investor to Private-Credit Powerhouse
Northwind began as an equity investor before expanding into real estate debt. In 2017, banks started pulling back hard on transitional commercial real estate, condominium inventory, and healthcare credit, but developers and sponsors still needed speed and certainty.
“We saw a clear opening to launch a discretionary credit platform focused on short-duration, first-lien debt where we could keep full control,” Eliasaf said. “Looking back, it was absolutely the right call.”
The strategy gives borrowers an alternative to traditional financing while allowing Northwind to structure loans around specific assets, sponsors, and business plans. The firm typically targets $10 million to $250 million checks, with a focus on New York, other major gateway markets, and South Florida.
He points to 685 Fifth Avenue, the Mandarin Oriental Residences conversion, as a case study. Northwind provided a $162 million construction loan in 2022 to get the building over the finish line, then returned in 2024 with a $120 million inventory loan on the remaining units.
“Same asset, same sponsors, but we adapted as the risk profile evolved,” he said. “Across the entire platform, we’ve originated billions in real-estate-secured loans with zero principal loss and no REO.”
Financing the Final Mile of NYC Development
Northwind has carved out a role in projects that need completion financing, condo inventory loans, or capital to carry finished units through a slower sales cycle.
At 125 Greenwich Street, Northwind provided $313 million in completion and condo inventory financing for the 88-story luxury condominium tower in Lower Manhattan. The project is backed by a joint venture involving Fortress Investment Group, Bizzi & Partners, and U.S. Immigration Fund.
The firm has also expanded its exposure to office conversions. In September 2026, Northwind provided a $219 million construction loan for 100 Wall Street, where BLDG and David Werner Real Estate Investments are converting part of a 463,000-square-foot office tower into 168 rental apartments while retaining office space on upper floors.
For Eliasaf, these deals are not necessarily distressed-property bets. Some projects simply need additional time and capital to reach completion or sell remaining inventory.
“If the basis is sound, the product is premium, and the sponsor can execute, we’ll fund the final mile,” he said.
Why Underwriting Discipline Still Matters
Northwind is avoiding high-loan-to-cost construction projects with limited presales, speculative office deals, and weaker sponsors. Its typical loan duration is approximately 18 months, and Eliasaf says the firm does not assume aggressive interest-rate cuts will rescue a transaction.
Instead, underwriting focuses on individual units, comparable sales, sponsor track records, and the stage of construction or sellout. When sales slow, Northwind may require borrowers to contribute additional equity.
That caution is especially relevant as private credit expands. A recent Reuters report noted that private-credit fundraising is rising even as lending activity slows, increasing pressure on lenders to deploy capital. For real estate investors, the implication is clear: access to financing matters, but loan terms and sponsor credibility remain critical.
Healthcare Lending Adds Another Growth Engine
Beyond residential real estate, Northwind has invested heavily in skilled nursing and senior housing. Eliasaf said the firm has deployed more than $4.6 billion across 400 properties in 26 states, with roughly 70% of that activity concentrated in skilled nursing.
The firm focuses on cash-flowing portfolios operated by experienced businesses, with a clear refinancing path to HUD financing. It avoids single-asset healthcare loans and ground-up construction in that sector.
The strategy reflects a broader principle: specialized knowledge matters when a lender is evaluating operational businesses alongside the underlying real estate.
The Long-Term Bet on New York
Eliasaf remains bullish on New York because of its housing shortage, even as higher borrowing costs slow transactions and challenge development budgets.
He expects office-to-residential conversions to deliver more housing and private credit to become a permanent part of the real estate capital stack.
Northwind’s $1 billion fund close gives the firm more capacity to pursue that opportunity. Its next challenge is maintaining the underwriting discipline that helped attract capital in the first place. For developers, that means private credit can offer speed and flexibility, but the strongest sponsors and most credible business plans are still likely to get the best hearing.
ABOUT THIS STORY
- Desk
- Articles
- Filed
- Nov 6, 2026
- By
- Traded Media